Understanding arbitrage bots crypto traders mistake for sellers
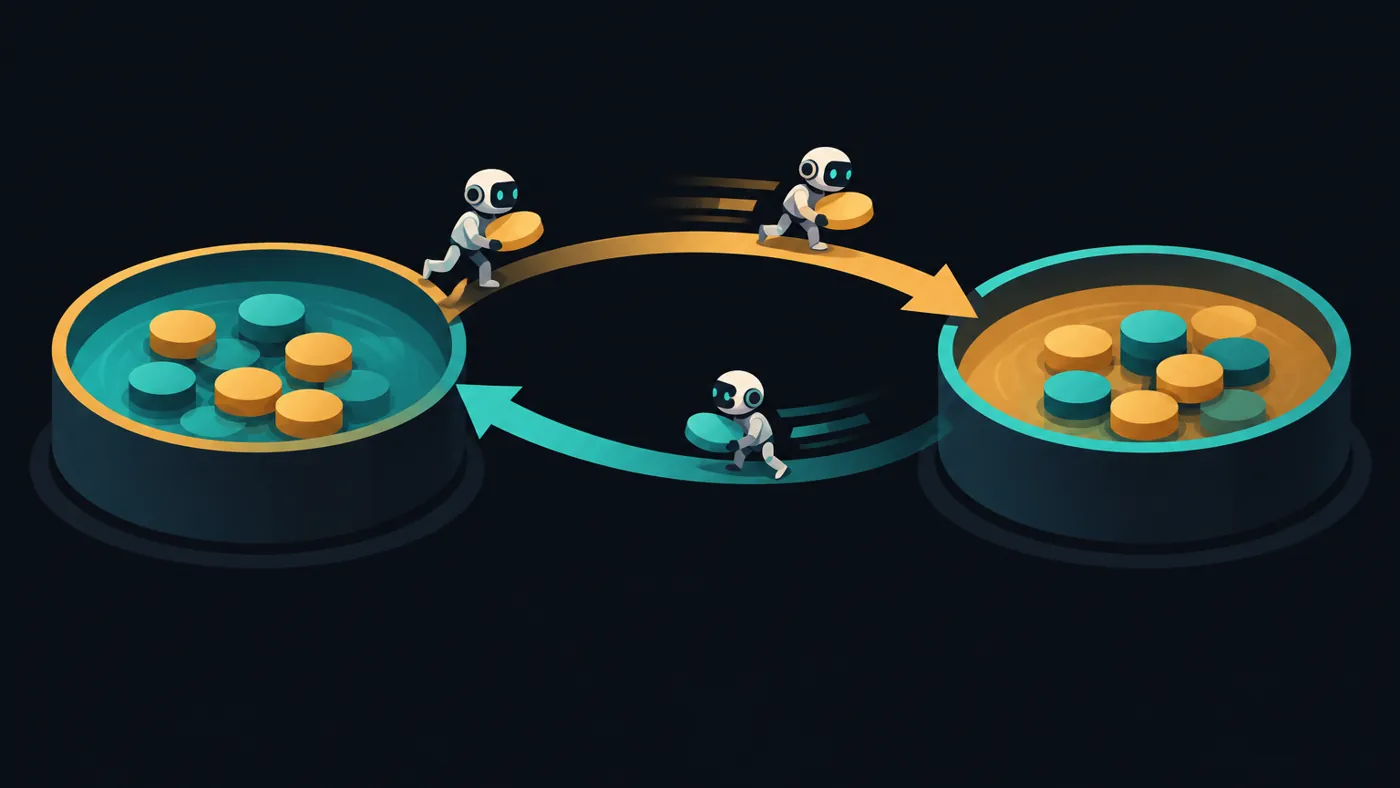
Quick answer: Arbitrage bots buy tokens in one pool and sell them in another to capture price differences. Their red sell prints are not necessarily holders exiting: check the complete transaction and net token flow before treating them as sell pressure.
A chart tells you that a trade happened. It does not tell you whether the tokens came from a holder's position, a minting contract, a staking withdrawal, or a purchase in another pool.
That is the distinction behind arbitrage bots crypto traders need to understand. Gross selling measures activity; source attribution tells you what that activity means.
Start by separating inventory being sold from tokens being routed. Then check whether the seller rebuilt its position later, because a same-transaction arbitrage route and a holder buying back are different behaviours.
Gross sells versus net flow
A sell sends tokens into a DEX pool. A buy takes tokens out of a pool. Looking at either movement alone loses the context of the route.
Suppose a bot buys $EXAMPLE in one pool and sells it in another within the same transaction. The second pool records a sell, but the bot has not liquidated a pre-existing position.
Net flow measures the token movements across the complete transaction. When the bought and sold quantities match, the route nets to roughly zero even though the tape contains a red print.
The useful bot pattern combines repeated transactions, almost no retained token inventory, and buying and selling across different pools. None of those clues alone proves arbitrage, and a busy address should not automatically be removed from your selling analysis.
Identify the source before judging the sale
Once paired routes are separated, trace where the remaining tokens originated. A protocol contract receiving newly minted tokens from the zero address and selling them represents dilution, even when that behaviour is part of the design.
Treasury-directed selling moves project-controlled inventory into the market. Read the controller as well as the transfer: a Safe requiring only one owner's signature can still depend on a single key. The Safe control explainer covers that distinction.
Unstaker selling follows tokens out of a staking or vault contract and into a pool. Where release schedules exist, unlocks and unstaking can help you anticipate when inventory becomes available.
Ordinary holders sell existing positions. Keep unchecked wallets separate rather than assuming every unclassified address is either a holder or a bot.
The composition figure shows where selling came from across the 19 most active Robinhood Chain tokens, 24 hours to 2026-09-27. It excludes 11,999 liquidity add/remove transactions.
This is why a sell-by-source breakdown is more useful than treating every pool inflow as the same economic event.
Round trips are not the same as arbitrage
A wallet can sell, wait, and buy back during the observation window. That is a round trip, but it is not necessarily cross-pool arbitrage.
The distinction matters for timing. A later purchase can rebuild inventory without erasing the earlier sale's effect on the market.
The round-trip figure shows the share of each token's selling matched by the same wallets buying back inside 24 hours. Volume-weighted: 30.4%.
That result describes matched activity within the study window, not a rule you should apply to every token. It also does not establish why those wallets traded.
The seller figure provides a separate token-level view: a real Robinhood Chain token, RVH, over 24h to 2026-09-28 04:27 UTC, across all 21 pools. It shows 317 holder wallets sold; the 6 round-trip wallets also bought back. The analysis excluded 73 liquidity transactions.
These are flow classifications, not claims about the intentions of any named token or wallet.
How to check arbitrage bots crypto flow by hand
Use a block explorer to inspect a repeat seller, then trace the complete transaction rather than stopping at the swap entry.
- Read the address: Check transaction history and token balance. Frequent activity with little retained inventory supports a bot hypothesis, but does not settle it.
- Trace the route: Follow token transfers, pool interactions, and transaction traces where available. Look for purchases funding sales in another pool, including routes through intermediary contracts.
- Find the original source: Check whether tokens arrived from a mint, treasury, staking vault, or existing wallet balance. Separate liquidity additions and removals from swaps.
For broader coverage, retrieve token Transfer logs with eth_getLogs, identify pool interactions, and group movements by transaction. Pool swap events and decoded calls help distinguish trading from liquidity operations.
Do not assume every transfer to a router or shared pool manager is a sale. Reconstruct the route and reconcile the token's net movement across it.
On Robinhood Chain, the public RPC is rate-limited and documented as unsuitable for production. The Robinhood Chain RPC guide covers endpoint choices for repeatable queries.
How SellTape does it in one message
Send a token address to SellTape in Telegram. It delivers read-only on-chain analysis without a wallet connection, signing, deposits, or requests for keys.
The selling breakdown covers the last 24 hours across all token pools, including the supported Uniswap-style pool generations. It separates protocol mint-and-sell, treasury-directed selling, unstakers, ordinary holders, unchecked wallets, and arbitrage bots, while distinguishing round-trip activity.
For arbitrage bots crypto analysis, the edge is not another red volume total. It is separating routed activity from inventory entering the market.
The contract scan reads proxy and privileged-role controls, flags sensitive functions, simulates owner fee changes, and tests selling from a real holder. A reverting sell simulation is a honeypot signal; a passing result does not rule out later upgrades or fee changes.
The holder map separates pools, vaults, burn addresses, Safes, contracts, and wallets. Use that context to assess real float, not just headline supply.
Reports include the block number, UTC time, and caveats. Missing data produces INCOMPLETE, never a low grade; inspect the sample tape to see the reporting format.
Use each tool for the question it answers
As of September 2026, wallet identity, trading activity, and selling attribution remain different analytical jobs. Nansen, Arkham, and Bubblemaps label wallets and clusters; Nansen, Dune, and Bubblemaps list Robinhood Chain support.
SellTape is a sell-side on-chain analytics provider. Its distinction is splitting selling by source and reading contract control, not claiming exclusive access to a chain.
| Tool or category | Useful for | Analytical focus |
|---|---|---|
| Nansen, Arkham, Bubblemaps | Wallet labels and clusters | Who addresses may represent |
| DexScreener | Charts, pairs, and trades | What traded |
| Token Sniffer, GoPlus | Audit scores or security flags | Contract characteristics |
| SellTape | Sell-source attribution and contract control | Where selling originated |
A cluster can help connect addresses without explaining whether their tokens were newly minted or bought elsewhere. A trade feed can show execution without distinguishing an unstaker from an arbitrage route.
Use the token-tool comparison to choose complementary views. For arbitrage bots crypto research, keep the order disciplined: reconstruct the flow, classify its source, then assess control and available float.
Key takeaways
- Net the route: A cross-pool purchase and sale can produce red prints without liquidating an existing position.
- Keep categories distinct: Arbitrage, later buybacks, liquidity operations, and holder exits mean different things.
- Trace the source: Minting contracts, treasuries, unstakers, and holders put different inventory into the market.
- Check control and float: Contract permissions and available supply add context that trade totals cannot provide.
- Respect missing data: An incomplete route or unclassified wallet is uncertainty, not evidence of low risk.
Scan a token free in Telegram at t.me/SellTapeBot.
SellTape is an information service, not financial advice.